
Three years ago I set out to answer what sounded like a simple question: across the G20, how has demand for tax-technology and AI capability moved relative to traditional tax jobs?
The question could not be answered as asked. There is no standardised occupational category called “tax technology.” The capability is advertised under a dozen different titles — Tax Technology Manager, Indirect Tax Technology Manager, ERP Tax Consultant, Tax Data Analyst, E-Invoicing Consultant, Tax Technology Solution Architect, Tax Transformation Manager — and salary disclosure varies so widely by jurisdiction that a like-for-like count is not available. Any number I produced would have been invented.
But the failure was more useful than the answer would have been, because it exposed the wrong assumption underneath the question. I had been asking which jobs were growing and which were shrinking. The more accurate question turned out to be: where is tax work being done now, and where will it be done next?
That reframing is what this research is about. Tax expertise is not disappearing. Tax work is changing location — and professional value is moving with it.
How to Read the Evidence in This Research
Before any of the numbers, one methodological point, because it determines how much weight each of them can carry.
Three classes of evidence appear below and they are not interchangeable. Institutional evidence — OECD reports, ICAI publications, tax-authority guidance, mandate instruments — is cited directly. Survey evidence from Deloitte, PwC, EY and Thomson Reuters records what tax leaders report believing and intending; it is evidence about expectation, not about observed employment. Company-reported evidence — the customer counts and transaction volumes published by tax-technology vendors — is treated as directional and identified as such.
The editorial rule I applied throughout: every figure must carry a source, a date, a definition and a denominator. Figures that could not carry all four were removed rather than qualified. Several were — including some that would have supported the argument.
Tax Expertise Is Not Dying. Tax Work Is Relocating.
The evidence of the last three years is routinely read as a contradiction, and the contradiction dissolves once you look at what is actually being measured.
On one side, the World Economic Forum's Future of Jobs Report 2025 places accountants and auditors among the occupations employers expect to decline through 2030, naming “broadening digital access, AI and information processing technologies, and robots and autonomous systems” as the primary drivers. On the other, PwC's 2025 Global Reframing Tax Survey found 95% of respondents reporting a tax-function skills gap, with 55% describing it as very wide.
Both are true, and the WEF data says something more precise than it is usually reported as saying. The WEF treats the profession as two separate occupations and forecasts them very differently. “Accounting, Bookkeeping and Payroll Clerks” sit near the top of the fastest-declining list, with a projected contraction of roughly 18 to 20 per cent. “Accountants and Auditors” appear considerably further down the same list, at approximately 5 per cent.
The gap between those two numbers is this entire thesis expressed in the WEF's own taxonomy. What employers expect to disappear is the clerical layer beneath professional accounting judgement — the recording, matching, transcribing and processing work that has historically surrounded professional judgement and, in a great many firms, quietly subsidised it.
Four statements make the reconciliation concrete:
- AI can reduce the labour required to research legislation without eliminating the need to decide how legislation applies.
- Automation can reduce return preparation without removing responsibility for whether the underlying transactions were taxed correctly.
- E-invoicing can automate transmission while making master data, tax determination and transaction design more important.
- A tax engine can calculate tax at enormous scale — and make errors in its configuration enormously scalable at the same time.
The professional therefore moves from performing each transaction to governing the logic that determines millions of transactions. That is a change in professional leverage rather than a straightforward substitution of machine for person.
What Three Years of Evidence Actually Show
Arranged chronologically, the shift becomes unusually visible.
2023 — data becomes the capability gap
Deloitte's Tax Transformation Trends 2023 (300+ senior tax and finance executives) found 44% identifying data analytics, data-driven insight and data management as the area of greatest skill need over the following three to five years. Deloitte gave the emerging profile a name: the hybrid tax professional.
The same survey showed the mechanics of delivery beginning to move: 53% pointed to greater use of shared-service centres, 48% to migration of activity from tax to other business teams, and 40% to third-party outsourcing. That 48% is worth separating out, because it is frequently misread as an outsourcing figure. It is not. It describes work moving inside the organisation, away from the tax department — which is a different and in some ways more consequential phenomenon.
2024 — expectations move before workflows do
EY's 2024 Tax and Finance Operations Survey — 1,600 respondents across 32 jurisdictions, comprising 1,100 tax and 500 finance leaders — found 87% believing that integrating generative AI would drive increased efficiency and effectiveness within the tax function.
EY contrasts this with a figure of 15% which it attributes to 2023. I do not present that as a measured series and neither should anyone else: EY does not publish the 2023 question wording or sample, and the two questions as described measure different things — whether the technology “would have an impact” versus whether integrating it “will drive increased efficiency and effectiveness.” A seventy-point movement in twelve months is at least as likely to reflect a change in the question as a change in belief.
What can be said without qualification is that by mid-2024 an overwhelming majority of tax and finance leaders expected GenAI to improve the tax function. Investment, recruitment and role design tend to follow expectation long before they appear in occupational statistics.
2025 — AI becomes a talent problem
By 2025 the question had moved from whether AI would matter to who could actually use it. Deloitte surveyed 1,000 senior tax and finance leaders and found 57% considering AI skills essential to the tax workforce today, and 94% expecting them to be essential by 2029. Asked about capability needs over the following two years: 45% named specialist AI skills, 42% data analytics, and 36% specialist tax technical capability. Fifty-three per cent were actively recruiting digitally native technology and AI talent.
PwC's Reframing Tax survey, covering 1,205 respondents across 47 countries, identified the three capabilities most critical to closing the skills gap as AI knowledge, specialised tax expertise and data analysis.
That list places specialised tax expertise alongside AI and data as co-equal requirements, which is a different claim from technical skill displacing tax expertise. The profile was no longer tax or technology. It was tax and technology and data.
2026 — ownership arrives ahead of capability
The 2026 Thomson Reuters Corporate Tax Department Technology Report is the most quoted organisational evidence in this space and the most frequently over-read. Its sample is 170 US-based corporate tax decision-makers, with fieldwork in November and December 2025 — narrower than the global surveys above, and it should sit alongside them rather than be merged into them.
Departments with a dedicated person responsible for tax technology strategy rose from 51% to 88% year on year. That movement is real and significant. But in roughly two-thirds of cases, the person holding that responsibility is the head of tax. The figure records the formal assignment of ownership far more than the creation of specialist posts.
Meanwhile the most common expectation for AI becoming central to workflows shortened from three-to-five years to one-to-two. Approximately two-thirds reported that technology investment had moved their departments towards more strategic work.
And at the same time — this is the finding that should not be softened — 64% described their department as chaotic or reactive, up from 57% the previous year. Dissatisfaction with technology stacks rose from 34% to 56%. The proportion describing themselves as very satisfied fell from 11% to 4%. Thomson Reuters frames the whole report around what it calls a frustration gap.
Read together, those numbers say something specific: ownership is being assigned faster than capability is being built, and expectations are compressing faster than maturity is improving. Over the past year, departments became more aware of what they needed and less satisfied with what they had.
These findings are consistent with a widening capability gap. That gap is where the professional opportunity sits.
Governments Became Technology Organisations Too
The private sector is only half of the transformation. The other half is the tax authority, and it is the half most career discussions ignore entirely.
Two OECD sources matter here. Because they draw on different samples and survey rounds, they belong in separate sentences rather than a single series.
Tax Administration 2025 covers 58 jurisdictions and reports fiscal year 2023 data. Within it, the OECD sets out its own ten-year comparison of AI adoption: from 9% of administrations in 2016 to 69% in 2023, with a further 24% in the implementation phase. Those two figures are response options on one question and together account for 93% of the jurisdictions surveyed.
Tax Administration Digitalisation and Digital Transformation Initiatives, published June 2025, covers the 54 members of the Forum on Tax Administration. It reports that more than 70% of those administrations use AI, most commonly for fraud and evasion detection, followed by risk assessment and virtual assistants. From the same report:
- More than 80% are developing APIs, and over three-quarters of those make at least some publicly available.
- Approximately 80% receive data directly from taxpayer business systems, beyond standard payroll information.
- Close to 40% can pre-fill VAT returns — though only around 30% of that group provide returns complete enough to require no taxpayer changes.
- Around one quarter pre-fill corporate income-tax returns.
- Nearly 80% have a digital-transformation strategy, with a similar proportion running senior-management governance over it.
One caveat, stated by the OECD itself: the inventory data underlying that second report is self-declared by the administrations and was not independently validated.
The consequence for the taxpayer is structural. A company historically had weeks or months between an operational transaction and detailed authority scrutiny. Increasingly, the authority holds structured information at, or very close to, transaction time.
Why Value Moves Upstream: The Tax Velocity Gap™
The Tax Velocity Gap™ describes the shrinking interval between a business transaction, the creation of its tax record, and structured visibility to the tax authority.
Under periodic reporting, that interval was generous, and the tax function quietly depended on it for something it rarely named out loud: time to repair the past. The historic chain ran transaction → accounting → reconciliation → tax review → adjustment → return → authority. Six opportunities to correct something before anyone outside the business saw it.
The emerging chain runs transaction → structured tax representation → authority visibility. There is no repair window in it.
Once that window closes, tax cannot primarily be a downstream review function. It has to influence the point at which the outcome is created — customer and supplier master data, product classifications, tax codes, transaction logic, ERP configuration, billing architecture, procurement workflows, e-invoice mappings, evidence requirements, exception handling and automated controls.
This is why tax-technology employment is rising even though tax law did not suddenly become technology. The location at which the tax outcome is created has changed.
Three related consequences follow, each with its own framework:
The Authority Mirror View™ describes the increasingly structured representation of a taxpayer's transaction universe available to the authority. A professional who understands law but cannot interrogate transactional data now sees only part of the risk, because tax judgement increasingly operates over populations rather than over documents. The requirement is fluency with transactional data, some distance short of becoming a data scientist.
Tax-as-Code describes what happens when interpretation must be translated into executable system logic: law → approved interpretation → decision rule → tax determination → transaction data → structured reporting → evidence. The traditional professional determines the correct treatment of one complicated invoice. The modern enterprise needs that same interpretation to operate correctly across ten million.
The Continuous Controls Environment™ describes the governance architecture required when downstream review is too slow. The old model rewarded the person who found 500 errors after month-end. The new one increasingly rewards the person who redesigns the process so those 500 errors are never created.
And a warning that applies to all three: the Green Dashboard Paradox™. A system can prove that a file was transmitted, a field was populated, a validation rule passed and an API returned success. It cannot prove that the business interpretation was legally correct, the commercial classification right, the evidence sufficient, or that an ambiguous position will survive challenge. The better the technology becomes, the more it matters to understand what the technology actually proves.
The Capability Answer: Fusion Professionals™
If value is moving upstream, the obvious question is what capability moves with it. The usual answers — learn AI, learn Python — are wrong in an instructive way.
Fusion Professionals™ does not mean that every CA becomes a tax lawyer, software engineer, ERP architect, data scientist, AI engineer and project manager simultaneously. That would be unrealistic and economically inefficient. Specialists remain necessary.
The fusion capability is connective judgement: deep domain understanding plus enough adjacent fluency to recognise when another domain creates a tax consequence, to diagnose where a problem actually originates, and to hold the chain together across functions that do not report to you.
Specialists go deep. Fusion Professionals™ connect the domains.
Operationally, it is tax depth extended through four adjacent areas — data, technology, process design and orchestration — with evidence, controls and governance running underneath. It is a capability architecture underlying many job titles rather than a forecast of one.
There is a reason connective judgement is becoming scarce, and it has a name: Cognitive Responsibility Diffusion™. Procurement owns vendor onboarding. Sales owns customer information. IT owns ERP configuration. Data teams own master-data architecture. A vendor owns transmission. An AI model may recommend the treatment. And the tax function remains accountable for the tax outcome. Automation does not remove accountability; it disperses the causal chain while leaving accountability exactly where it was. Someone has to own that chain. That is an orchestration role, and it is the one the market is short of.
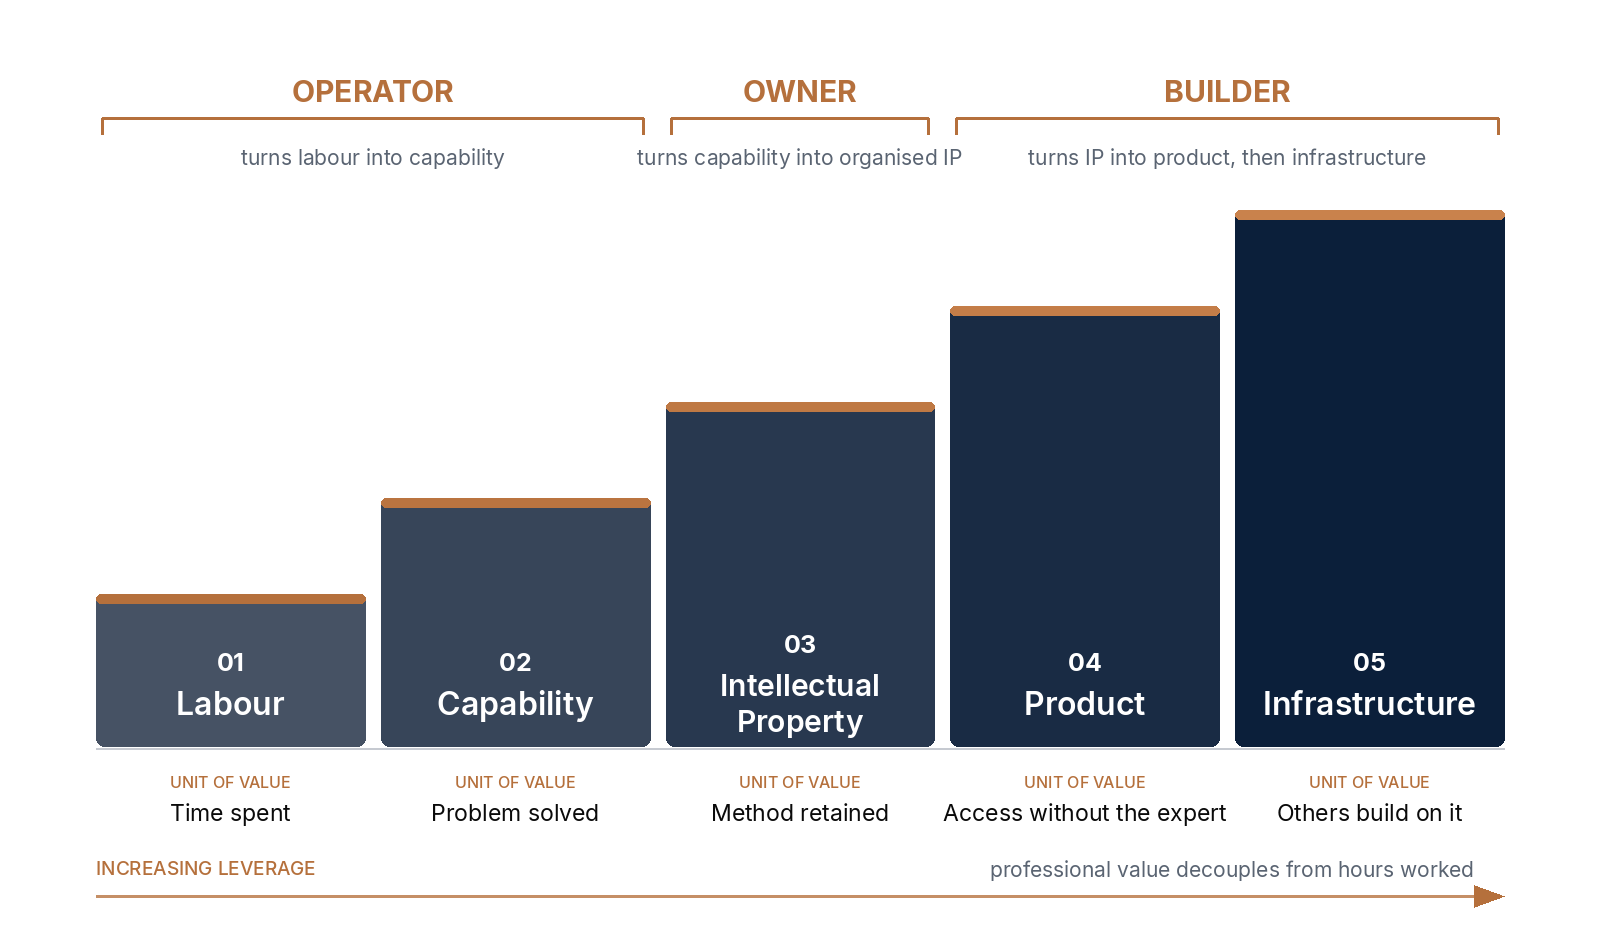
Operator → Owner → Builder™
Capability is the answer to “what should I know.” It is not the answer to “what should I do with it.” That question has three economically distinct answers, and the distinction is not about status.
The Operator
The individual professional inside a firm, multinational, consultancy, shared-services centre or authority. The economic question is: how do I move from selling my labour to selling scarce capability?
The answer is a stack, and the sequence matters more than any individual layer: tax knowledge → transaction understanding → ERP literacy → data capability → digital-tax capability → transformation capability → AI capability → leadership and orchestration.
The near-universal mistake is jumping from the first layer to the seventh. A CA who understands tax law but not where the relevant data originates cannot govern an AI model analysing that data. A professional who does not understand purchase-to-pay or order-to-cash cannot diagnose why a tax treatment is failing upstream. One who has never worked through requirements, testing and implementation will struggle to turn an AI prototype into production capability.
Employers are now describing this stack in their own words. EY currently advertises a Digital Tax Administration role at senior-associate level requiring three years of implementation experience and at least one year of hands-on e-invoicing experience, naming SAP DRC, Pagero and Edicom, with duties described as analysing ERP data structures, mapping them to government portal requirements, and developing the connectors, mappings and transformations that carry them. Tax, ERP, data mapping, integration and digital reporting — in a single job description, below manager grade.
Anthropic makes the same point from the opposite direction: it advertises a Finance Systems Engineer for Tax who must write production Python and SQL and build audit-ready data pipelines, and separately an eight-year indirect tax specialist who has implemented Avalara, Vertex, Sovos or TaxJar. Neither company is recruiting an AI model to do tax. Both are recruiting humans capable of governing tax across a sophisticated technology environment.
The route through the stack is not uniform, and treating it as one is poor advice. A newly qualified CA should build data, process and ERP literacy before specialising. A professional with two to four years of GST or VAT experience already holds valuable domain capital and should add transaction-cycle understanding, analytics and e-invoicing rather than restart. A statutory-audit professional with three to six years should not assume they need to go back to basic tax — their process, controls, reconciliation and evidence instincts translate directly into the assurance side of automated tax. And a tax professional with five to eight years should rarely reset to analyst level; their better move is to engineer the next project. Lead an e-invoicing workstream. Join an ERP migration. Own a tax-data remediation. Run UAT. The transition happens through an implementation, not through another collection of certificates.
Which raises the question of what a professional at any of those stages should actually build. Four projects, in sequence, produce artefacts that demonstrate rather than assert capability. A tax data health exercise over a synthetic dataset of tens of thousands of purchase and sales transactions — cleaning, de-duplicating, testing rates, validating registration identifiers, reconciling to ledger totals, categorising exceptions. A tax determination design for a fictional multinational, translating ship-from, ship-to, customer status, product and registration into treatment, tax code, invoice treatment and expected accounting result. An e-invoicing implementation pack for a mandate-affected company: field mapping, master-data requirements, exception handling, rejection scenarios, controls, reconciliation, evidence, UAT scripts. And only then an AI-enabled workflow, documented for input data, decision boundaries, human approval points, accuracy risk, audit trail and governance.
The sequence is the point. The fourth project proves AI capability rather than AI familiarity precisely because the first three came before it.
The Owner
The professional firm. The economic question is: how does my practice solve problems larger than compliance execution?
This matters enormously in India, where the profession is overwhelmingly composed of small practices — on ICAI's own firm data, sole proprietors and individual practitioners account for approximately 72.6% of registered CA firms, and roughly 98% have five or fewer partners.
That structure is usually read as fragmentation. Read correctly it is an extraordinary distribution network already in place. The practitioner in Indore, Surat, Guwahati, Jaipur, Coimbatore, Nagpur or Rajkot does not need to find the entrepreneur. They already know the accounts, the GST history, the cash-cycle problem, the vendors, the bank, the ownership structure, the software and the control weaknesses.
The problem is not customer access. The problem is what capability the firm sells to that customer.
The progression out of the labour model is more concrete than “become a consultant,” which is advice too abstract to act on. It runs in stages, each of which sells something the previous one could not. Automate the practice itself before advising anyone else on transformation — the firm's own transformation becomes its first case study. Move from filing to finding: instead of telling a client the return was filed, tell them that ₹8.2 lakh of input tax remains unreconciled, that three suppliers account for 63% of repeated exceptions, and that the same error pattern has run for four months. Fix the process that creates the error, which means learning enough purchase-to-pay, order-to-cash and record-to-report to say where a defect originates and what control change prevents it. Implementation: readiness assessment, gap analysis, data remediation, testing, go-live assurance. Assurance around automation, which plays directly to the profession's heritage — the vendor proves the invoice transmitted; the CA asks whether it was complete, correctly treated, fully reconciled and defensible. Fractional capability, where the monthly conversation expands from filing into tax risk, working capital, data health and control exceptions. AI advisory, where the professional value lies in knowing where a model belongs, what data it can trust and where human responsibility must remain. And finally global delivery, where digital delivery decouples the practice from its geography.
ICAI's own materials describe a comparable arc — its How to Grow Your Practice booklet sets out a progression from digitisation to automation to integration and intelligence, and its 2026 programme is themed around scaling through advisory, specialisation and global integration. The Institute has also widened what a Chartered Accountant may sell: the thirteenth edition of the Code of Ethics, applicable from 1 April 2026, expanded Management Consultancy and Other Services to include artificial-intelligence-related services. Worth reading precisely, though — that is a liberalisation of permitted scope, not an ethical framework for how CAs should use AI in their own work. The Institute has widened the door; it has not yet written the rules for the room.
And here is the correction that most versions of this argument omit. Automation creates available time, not advisory capability. A firm that automates GST reconciliation can spend the benefit four ways: cut prices, take on more compliance clients, give partners their evenings back, or build diagnostic and advisory services. Only the fourth changes the economic model, and it is the least likely default. Automation is a necessary but insufficient condition for practice transformation. The route through requires four deliberate investments — capability, commercial design, organisational redesign, and the slow work of teaching clients to buy insight rather than filings.
The Builder
The professional who asks a different question entirely: I have solved this problem twenty times. Why should a human solve it from scratch the twenty-first time?
It is worth looking at who actually occupies this layer, because the definition makes more sense arriving second.
Roger Gothmann met the complexity of international VAT from inside a tax administration, after more than a decade as an auditor and official including at Germany's Federal Central Tax Office; he co-founded Taxdoo in 2016 with two fellow economics doctorates. Maria Scott met the cost of FATCA and CRS compliance from inside a global financial institution, after roughly two decades as a tax lawyer, and founded TAINA. Benjamin Alarie met the limits of manual tax research as a law professor at the University of Toronto, and co-founded Blue J in 2015 with two colleagues from the same faculty. Fonoa's founders met global tax complexity while scaling Uber across jurisdictions.
None began as a technologist with an interest in tax. Every one began as a domain practitioner with a problem that would not go away. Their starting points differ; their sequence does not:
domain expertise → repeated pain → method → codified knowledge → product → infrastructure.
Which means the first Builder question is not “what app should I build?” It is: what valuable knowledge exists inside my head, or my firm's processes, that we reproduce manually over and over? Productisation can begin with a diagnostic, a decision matrix, a rules library, a control framework, a testing library or a scoring methodology. Software may come much later, or never.
A worked example makes the ladder concrete. Consider an Indian practitioner who has reconciled input tax for a hundred businesses. At the labour stage the offer is “send the purchase register, my team will reconcile it.” At the capability stage it becomes “we will diagnose why credit repeatedly leaks.” As a productised service: “upload your data, we apply a defined set of risk tests and return a GST input tax health score.” At the IP stage the practitioner codifies the rules — duplicates, GSTIN quality, rate anomalies, ageing, vendor patterns, credit notes, reverse charge, master-data exceptions, matching logic. As a tool, a customer uploads data and the rules engine surfaces exceptions. As a product, continuous monitoring becomes a subscription.
And then the interesting step. The builder stops thinking “Indian GST reconciliation” and starts thinking inbound tax assurance. The same abstract problem exists in UAE VAT, Saudi VAT, European VAT and most transactional tax systems: can the buyer trust, support and defend the tax generated by inbound transaction data? The regulation changes. The underlying problem is remarkably portable.
E-invoicing is a particularly fertile laboratory for this, because every implementation contains the same repeatable knowledge — country requirements, invoice fields, schema rules, tax codes, master-data requirements, ERP mappings, rejection logic, test scenarios, reconciliation, controls and evidence. A professional does not have to build another global transmission network. They could productise one narrow expensive problem extremely well: readiness diagnostics, data-quality checking, field mapping, tax-code validation, UAT automation, exception triage, control monitoring, regulatory-change intelligence or evidence governance. Large markets are frequently created by solving narrow problems properly.
One caution about the evidence in this layer, since it is the layer where claims are loosest. Every customer count and transaction volume published by the companies named above is company-reported, and in preparing this research I found that five of the six publish materially inconsistent figures across their own websites and press materials — in one case two different customer counts in separate sections of the same page. That inconsistency is itself instructive about the maturity of the sector, and it is a reason to treat vendor metrics as directional rather than as measurement.
Three models, one profession
A successful professional does not have to become a founder, and a founder does not have to build venture-scale software. The Operator sells their capability. The Owner sells the firm's capability. The Builder sells an encoded version of capability. The leverage changes at each level; the underlying expertise does not.
Why India Sits Unusually Well in This
For decades India has exported professional labour with considerable success. A qualified CA could move to Dubai, London, Singapore, Toronto or Sydney, and that route remains valuable.
Technology introduces a second model: the professional does not always need to travel. Their capability can — through remote advisory, shared capability centres, specialist implementation teams, data and controls centres, managed tax technology, and eventually software.
The ingredients are unusual and genuinely difficult to replicate: a very large pool of professionally trained accountants; lived operating experience inside one of the world's most digitised indirect-tax regimes, through GST, e-way bills and e-invoicing; a major software and engineering ecosystem; English-language delivery; and global legitimacy in professional services already established.
The missing connection is usually between those ecosystems rather than within any one of them. Tax knowledge sits with the CA. Technology knowledge sits with engineers. Process knowledge sits inside businesses. Data capability sits somewhere else again. The opportunity belongs to whoever can connect them — which is precisely the problem the Fusion Professional addresses.
One distinction determines whether this becomes a large opportunity or a repeat of an old one. If a task costs US$100 an hour in London and US$20 in India, moving it to India creates value — but that is labour arbitrage, and AI applies pressure to exactly those repeatable activities. The durable model is knowledge arbitrage: the Indian team possesses capability that is difficult to find anywhere. Multi-country e-invoicing testing. ERP tax design. Indirect-tax data engineering. Tax-engine implementation. Transaction assurance. Master-data governance. AI-enabled tax controls.
Then India competes on being better at a specific scarce problem, and price stops being the argument.
A note on scope, since these markets are frequently discussed as one: they are not. Brazil, Mexico, India, Italy, South Korea, Saudi Arabia and Türkiye have transaction-level digital reporting experience. France and Germany are mid-implementation — and France's obligation is more immediate than usually described, with every French VAT-registered business required to be able to receive structured e-invoices from 1 September 2026, no size threshold, with issuance phased from that date for large and mid-sized enterprises and from September 2027 for the rest. Germany's receiving obligation has applied since January 2025, with issuance phasing from 2027. The United States, Canada, United Kingdom and Australia are driven far more by tax engines, ERP transformation, Pillar Two and provision than by clearance models.
The regulatory architectures differ. The professional capabilities travel across all of them. That is the point.
What to Do With This
The evidence points somewhere more specific than either panic or complacency: routine downstream execution is being compressed while upstream capability — design, governance, data, evidence, orchestration — becomes more valuable, and the professionals who move with it will be the ones who deliberately built the stack rather than the ones who waited to see what happened.
Three honest cautions before anyone acts on that.
First, the work does not move upstream automatically. The professional has to move with it, and nothing in the evidence suggests that happens by default.
Second, the apprenticeship problem is real and largely unaddressed. Junior professionals historically learned judgement by doing hundreds of reconciliations, returns and working papers. Much of that was inefficient — and it was also hidden training. PwC finds that the most AI-exposed entry-level jobs are already seven times more likely than the least AI-exposed to demand skills traditionally associated with senior employees. If AI removes the labour without replacing the learning architecture, firms will produce professionals who can operate AI systems but cannot tell when those systems are wrong.
Third, proof will matter more than certificates. The market pays for evidence that a problem can be solved, which a course completion does not supply. “Completed Power BI certification” and “built an indirect-tax exception model over 50,000 transactions identifying duplicate invoices, tax-rate anomalies, missing tax identifiers and ledger-reconciliation exceptions” are not the same claim, and only one of them demonstrates capability.
This research continues in a series of cornerstone articles working through each layer — what the evidence says about tax jobs specifically, the capability stack in sequence, the practice transition, and the route from professional knowledge to product. Each will be published here as it is written.
The profession has spent a great deal of energy debating whether AI will replace humans. The better question is which human activities remain economically valuable once machines can perform much of the execution. On the evidence: judgement, design, governance, interpretation, problem definition, communication, orchestration and responsibility.
That should give the tax profession confidence. It should not give it comfort.
Related Reading
- The Tax Velocity Gap™ — why the repair window is closing and what that does to the tax function
- Fusion Professionals™ — the capability architecture behind real-time tax
- The Authority Mirror View™ — what the tax authority can now see, and why data becomes a professional skill
- The Continuous Controls Environment™ — governance when downstream review is too slow
- The Green Dashboard Paradox™ — what a successful transmission does not prove
- Tax Administration 3.0 — the architecture driving all of this